Alternatives to Borrowing: Other Ways to Cover a Bill
A loan isn't the only way to handle an unexpected expense. Depending on the bill and how much you need, one of these options may cost less.
Guide · 2 min read · Reviewed: October 27, 2026
In short
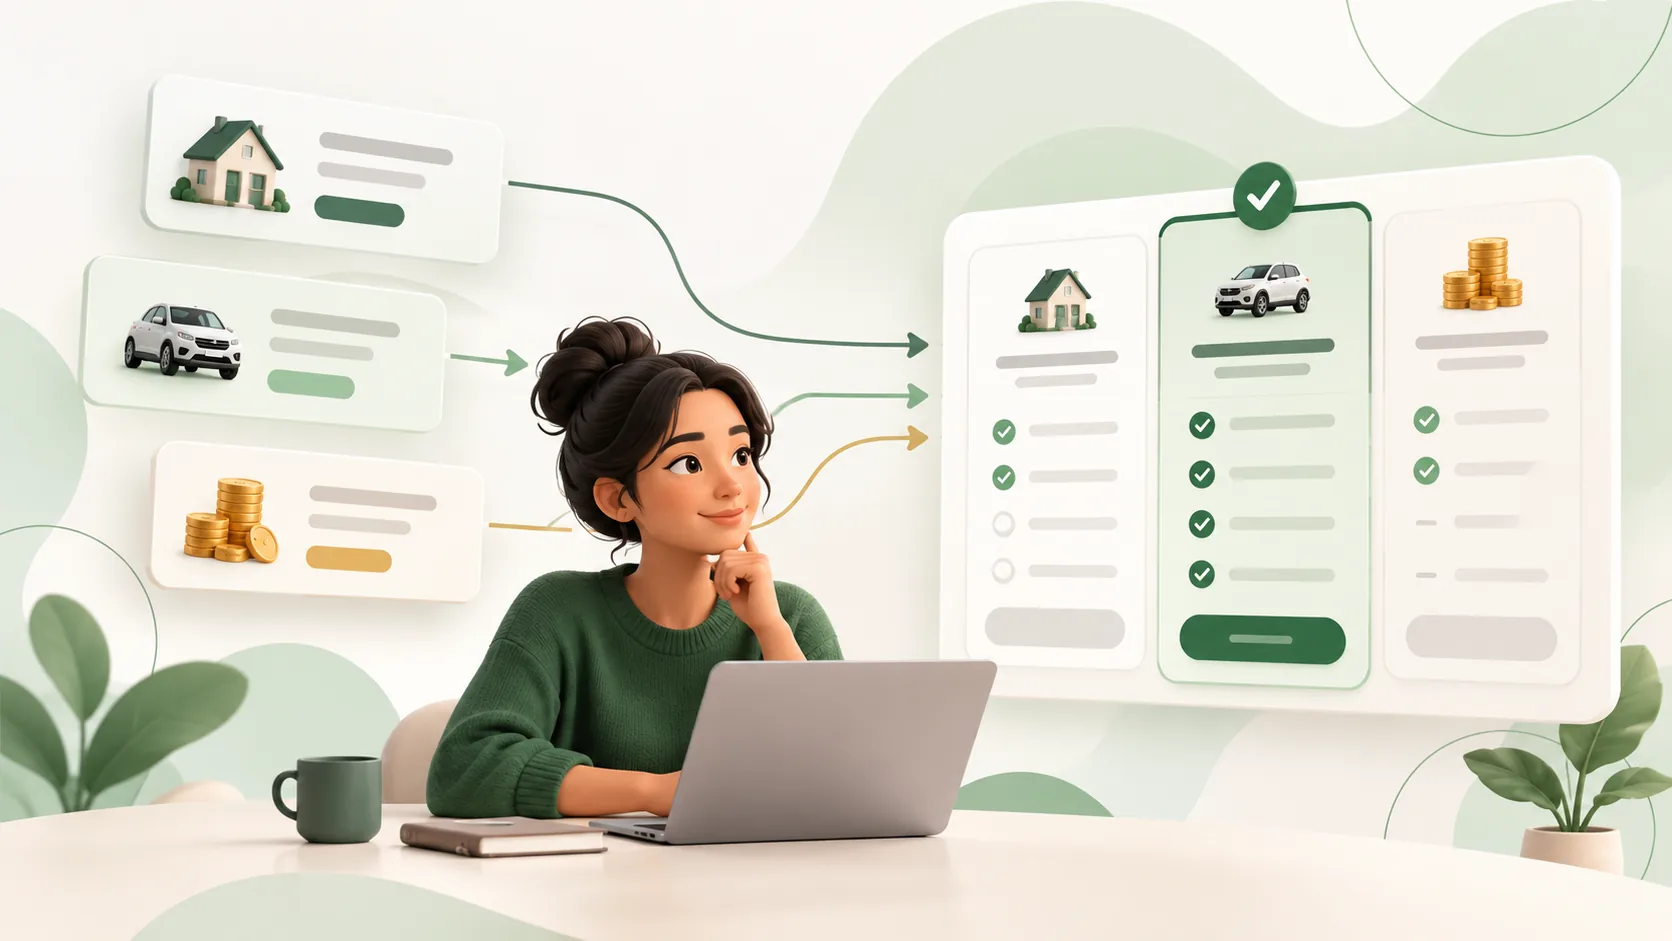
- Ask the provider about a payment plan first.
- Assistance programs can reduce utility, medical and housing bills.
- Cash advance apps can cover small gaps, but fees add up.
- A personal loan may fit larger costs repaid over time.
Your options at a glance
| Option | Often best for | Cost to watch |
|---|---|---|
| Payment plan | One bill from one provider | Any plan fees or interest |
| Assistance programs | Utility, medical or housing bills | Usually none, but eligibility rules apply |
| Cash advance app | A small gap until payday | Subscriptions, instant-transfer fees, tips |
| Credit union loan | Members needing a small loan | APR and application fee |
| Employer pay advance | Workers whose employer offers it | Any fees |
| Personal loan | Larger costs repaid over time | APR and total repaid |
Payment plans
Many hospitals, dentists, repair shops and utility companies will split a bill into smaller payments, sometimes without interest. Call the billing office, explain your situation and ask what they can offer before the due date.
Assistance programs
- Energy bills: the federal LIHEAP program helps eligible households with heating and cooling costs.
- Medical bills: nonprofit hospitals are required to have a financial assistance policy, and many providers offer discounts to patients who qualify.
- Local help: dialing 211 connects you with local assistance for rent, utilities, food and more in most of the U.S.
Cash advance apps
Cash advance apps let you get a small amount before payday and repay it from your next paycheck. Many don't charge interest, but subscriptions, instant-transfer fees and optional tips can add up on a small advance, so compare the total cost.
Searching for a specific app? Read our Tilt guide to see how its cash advance works. Tilt App is not affiliated with Tilt (tilt.com).
Credit union loans
If you belong to a credit union, ask about small-dollar loans. Many federal credit unions offer payday alternative loans (PALs), which have capped rates and are available to members.
Employer pay advances
Some employers offer pay advances or early access to wages you've already earned. Ask your HR or payroll team whether it's available and what it costs.
Other options
- Family or friends: if you borrow, agree on the amount and repayment dates in writing.
- An existing credit card: can work for a short time, but carrying a balance gets expensive, and cash advances on a card usually cost more than purchases.
- Selling something you don't need: can cover a small gap without any repayment.
When a personal loan may fit
A personal loan may make sense when the cost is larger than these options can cover, or when you need to spread repayment over several months. Compare the APR and total repaid before you accept.
Common questions
More answers in the help center.
Is a payment plan better than a loan?
Often, if the provider offers one with little or no interest. A loan may fit better if you need to cover several bills at once or the provider won't offer a plan.
Are cash advance apps free?
Some don't charge interest, but many charge subscriptions or instant-transfer fees, or ask for optional tips. Compare the total cost before you sign up.
Where can I find local assistance?
Dialing 211 in most of the U.S. connects you with local programs for rent, utilities, food and other needs.